Between geopolitical calm and rate pressure: Markets remain on edge
After a week dominated by tensions in the Middle East, markets attempted to stabilize, albeit without strong conviction. Oil prices remain elevated, yields are holding firm, and central banks are adopting a more hawkish tone.
Review of the past week
The week was marked by a slight easing in geopolitical tensions, with signals of diplomatic openness between Washington and Tehran. However, this détente remains fragile: markets continue to react sharply to each statement, resulting in lower, but still persistent, volatility.
Market stress has gradually shifted from pure geopolitical risk to macroeconomic and monetary factors. The CAC 40 traded in a choppy pattern, supported early in the week by hopes of de-escalation, before being weighed down by rising sovereign yields. Meanwhile, rates continued to move higher amid a reassessment of monetary policy expectations.
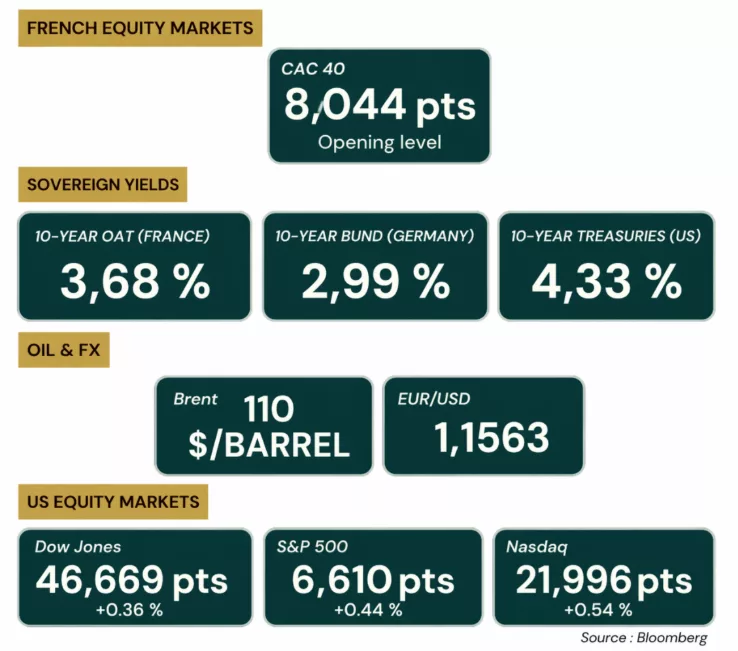
Key figures
• CAC 40
03/30: +0.42% → 7,721 pts | 04/04: −0.68% → 7,668 pts
• Brent crude
~ $112/barrel (peaking at $115 midweek)
• 10-year OAT (France)
03/30: 3.82% → 04/03: 3.68%
• 10-year German Bund
03/30: 3.09% → 04/03: 2.99%
• 10-year U.S. Treasury yields
03/30: 4.35% → 04/04: stable
Central banks: A shift in narrative
→ The expected pivot is clearly receding. The Federal Reserve is maintaining a restrictive stance, with no rate cuts expected in the near term. On the European Central Bank side, expectations have tightened significantly, with markets now pricing in three rate hikes in 2026.
Current policy rates overview
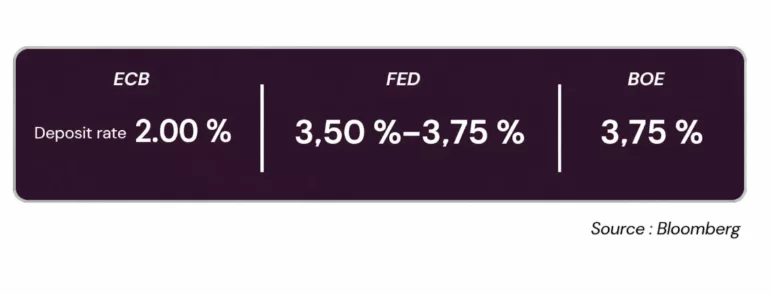
Summary of key figures for the week of April 06
Outlook and implications for treasurers
Markets appear to be gradually shifting from pure geopolitical risk toward a more structural macro-financial risk environment. Three key dynamics deserve close attention:
Dynamic 1: Persistently elevated rates
Rising yields are becoming entrenched, increasing pressure on funding costs.
→ In this context, issuance windows are becoming more tactical and require greater anticipation. Waiting for a potential pullback in rates risks ending up in a less favorable position.
Dynamic 2: Oil still under pressure
Brent remains above $110, sustaining persistent inflationary risks.
→ For corporates, the impact is direct: increased pressure on working capital requirements and reduced visibility on cash flows.
Dynamic 3: A less accommodative money market
The gradual widening of NEU CP / ECP spreads reflects tighter refinancing conditions.
→ In this environment, it is prudent to diversify funding sources.